Carbon capture and storage (CCS): How it works and why it matters
As the world grapples with the urgent need to reduce greenhouse gas emissions, carbon capture and storage (CCS) has emerged as one of the potential pathways for reducing CO₂ emissions from specified industrial activities.
In its Global Energy Perspective 2024, McKinsey projected that low-carbon energy sources would grow from 32% of global power generation mix today, to 65%-80% by 2050.1 But while renewable energy, electrification and other technologies are making strides in reducing emissions, they are harder to apply in sectors where operations are energy-intensive and rely heavily on industrial processes, often resulting in process emissions.
For hard-to-abate sectors including cement, waste, fertiliser production, power, chemicals and steel, CCS offers an important solution to help reduce emissions.
While the technology itself shouldn’t be seen as a standalone solution, it can play a key role within broader emissions-management strategies – helping businesses reduce emissions from specified operations while remaining economically competitive. For example, lower-carbon hydrogen is produced from natural gas through a process called steam methane reforming – whereby the CO2 emissions are captured and stored using CCS technology, making it a lower-carbon hydrogen option.2
Given its potential applications, how does CCS technology work, and how can governments and customers drive further adoption?
How does CCS technology work?
CCS typically follows a four-step process: capture, transport, storage and measuring, monitoring and verification:

Capture
The first stage involves separating CO₂ from other gases produced during industrial processes or fossil-fuel combustion in power plants. There are three primary methods3 to capture carbon: post-combustion, which extracts CO₂ from flue gases after fuel combustion using chemical solvents or adsorption techniques; pre-combustion, which removes CO₂ from fuel before combustion, typically in gasification processes; and oxy-fuel combustion, which uses oxygen instead of air for combustion, producing a flue gas primarily composed of CO₂ and water – simplifying CO₂ capture. Once captured, the CO₂ is then compressed into a liquid state and transported to storage sites.
Transport
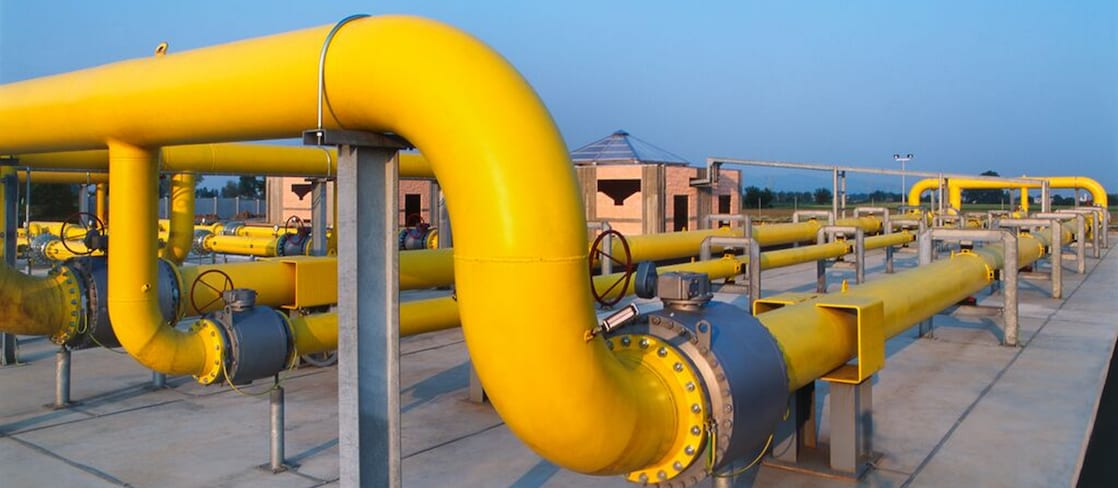
Transport can happen in a number of ways. Pipelines are a common method for moving large volumes of CO₂ – particularly for industrial clusters of interconnected companies and suppliers, which enables them to reap decarbonisation benefits. Ships can be used to transport cross-border liquid CO₂, particularly when storage sites are located offshore, making CCS technology viable even in hard-to-reach locations.
Storage
Once the captured CO2 arrives at the storage site, the final step involves injecting the captured CO₂ into the microscopic spaces in porous rocks, where one or more layers of impermeable rock, called cap rock, forms a seal to ensure it is securely trapped, offering permanent storage.
Measuring, monitoring and verification
Regular monitoring, both above and below ground, is implemented to ensure that the CO2 remains permanently and safely stored.
While CCS primarily focuses on capturing CO₂ from industrial facilities and power plants, Direct Air Capture (DAC) is an emerging technology that removes CO₂ directly from the atmosphere. DAC uses chemical processes to extract CO₂ from ambient air – making it particularly useful for addressing legacy emissions and carbon removal, which is why it is sometimes referred to as ‘negative emissions technology (NET)’.4 The CO₂ captured through DAC is either permanently stored underground or utilised in industrial applications, such as the production of synthetic fuels.
As DAC technology advances and becomes more cost-effective, it is expected to play an increasing role alongside CCS in emissions reduction strategies.5
Driving CCS adoption through policies and demand
Despite its potential, CCS faces economic and regulatory hurdles. Government support is essential to create a conducive environment for investment and deployment of the technology – including through policy frameworks, financial incentives, and infrastructure development across the full value chain.
For example, carbon pricing mechanisms such as carbon taxes or cap-and-trade systems – which set a tax rate on greenhouse gas emissions or the carbon content of fossil fuels and allow companies to trade emission allowances to meet compliance targets – can make CCS more economically viable6. Emissions reduction mandates to reduce carbon footprint across certain industries can incentivise adoption, while streamlined permitting and legal frameworks can accelerate the approval process for CCS projects.
Elsewhere, direct subsidies and grants can help to lower upfront project costs, and tax credits and incentives – such as the US’ Section 45Q Tax Credit for Carbon Sequestration which provides financial support – while public-private partnerships can help to share risks and mobilise investment in large-scale projects.7
Ensuring secure and efficient CO₂ sequestration requires strategic storage site development, which can only materialise if appropriate investments in infrastructure and transport networks are made. As such, encouraging industrial clusters whereby multiple companies benefit from shared CCS facilities can have a positive impact, helping to improve efficiency and scalability.
Beyond government support, market-driven demand for CCS can further accelerate adoption. Early adoption of the technology by companies in hard-to-abate industries can give them an edge over competitors in carbon-conscious markets where consumers increasingly prioritise low-carbon products.
Greater CCS demand and deployment can also lead to further improvements around the technology – with knowledge-sharing across sectors helping to accelerate cost-efficiency and commercial viability, for example.

CCS in action
Although CCS technologies are used in operating projects, it is not yet widely deployed and available. However, concrete examples of where it has supported documented CO₂ capture and storage activity already exist, with some projects in operation for nearly 20 years. Furthermore, according to the Global CCS Institute, while there are around 50 million tonnes per annum (mpta) of CCS in operation today, there are around 300 mtpa of projects under consideration and many net-zero scenarios show the industry growing to more than 1,000 mtpa by the mid-2030s.8

Quest: How CCS can help decarbonise Shell’s own operations
Northern Lights: Delivering CO₂ transport and storage as a service
Northern Lights is a CCS joint venture between Shell, Equinor and TotalEnergies, to develop the world’s first open-source CO2 transport and storage infrastructure, designed to transport captured CO2 from industrial sites across Europe and permanently and safely store it 2,600 metres below the seabed in the Norwegian North Sea. In 2025, Northern Lights announced plans to expand the transport and storage capacity of the project from 1.5 million to at least 5 million tonnes of CO2 per year.
CCS can be one option in the global effort to reduce greenhouse gas emissions, particularly in hard-to-abate industries. As demand for low-carbon solutions continues to grow, businesses can harness the potential the technology holds.
By aligning policy frameworks, financial support and market incentives, CCS can become part of broader efforts to reduce CO₂ emissions.
Date of publication: August, 2025

Carbon Capture and Storage (CCS)
CCS offers a way to reduce emissions, including from sectors that are slower-to-decarbonise. Learn more about this technology and how Shell is working to unlock its potential around the world.
Disclaimers
1 McKinsey, Global Energy Perspective 2024, September 2024
2 Shell Catalysts and Ventures, Blue Hydrogen Production
3 IPCC, Carbon Capture and Storage, 2005
4 Direct Air Capture Coalition, Frequently Asked Questions
5 IEA, Direct Air Capture, 2022
6 World Bank, What is Carbon Pricing?
7 Congress.gov, The Section 45Q Tax Credit for Carbon Sequestration, August 2023
8 Global CCS Institute, 2023. The Global Status of CCS 2023, November 2023
9 Shell, Quest Facility Spotlight: showing how large-scale CO₂ capture can be safe and effective
Disclaimer
Disclaimer
Cautionary Note
The companies in which Shell plc directly and indirectly owns investments are separate legal entities. In this content “Shell”, “Shell Group” and “Group” are sometimes used for convenience to reference Shell plc and its subsidiaries in general. Likewise, the words “we”, “us” and “our” are also used to refer to Shell plc and its subsidiaries in general or to those who work for them. These terms are also used where no useful purpose is served by identifying the particular entity or entities. ‘‘Subsidiaries’’, “Shell subsidiaries” and “Shell companies” as used in this content refer to entities over which Shell plc either directly or indirectly has control. The terms “joint venture”, “joint operations”, “joint arrangements”, and “associates” may also be used to refer to a commercial arrangement in which Shell has a direct or indirect ownership interest with one or more parties. The term “Shell interest” is used for convenience to indicate the direct and/or indirect ownership interest held by Shell in an entity or unincorporated joint arrangement, after exclusion of all third-party interest.
Forward-Looking statements
This content contains forward-looking statements (within the meaning of the U.S. Private Securities Litigation Reform Act of 1995) concerning the financial condition, results of operations and businesses of Shell. All statements other than statements of historical fact are, or may be deemed to be, forward-looking statements. Forward-looking statements are statements of future expectations that are based on management’s current expectations and assumptions, including (without limitation) those concerning Shell’s strategy and operating plans, macroeconomic conditions, future energy demand, supply and product mix, commodity prices, demand for Shell’s products, production results and reserve estimates, development, execution and management of projects, energy transition and climate change, management of safety and environmental risks, costs, cash capital expenditures, technology advancements, legislative, judicial, fiscal and regulatory developments, regional conflicts and trading conditions, and involve known and unknown risks and uncertainties that could cause actual results, performance or events to differ materially from those expressed or implied in these statements. Forward-looking statements include, among other things, statements concerning the potential exposure of Shell to market risks and statements expressing management’s expectations, beliefs, estimates, forecasts, projections and assumptions. These forward-looking statements are identified by their use of terms and phrases such as “aim”; “ambition”; ‘‘anticipate’’; “aspire”, “aspiration”, ‘‘believe’’; “commit”; “commitment”; ‘‘could’’; “desire”; ‘‘estimate’’; ‘‘expect’’; ‘‘goals’’; ‘‘intend’’; ‘‘may’’; “milestones”; ‘‘objectives’’; ‘‘outlook’’; ‘‘plan’’; ‘‘probably’’; ‘‘project’’; ‘‘risks’’; “schedule”; ‘‘seek’’; ‘‘should’’; ‘‘target’’; “vision”; ‘‘will’’; “would” and similar terms and phrases. There are a number of factors that could affect the future operations of Shell and could cause those results to differ materially from those expressed in the forward-looking statements included in this content, including (without limitation): (a) price fluctuations in crude oil and natural gas; (b) changes in demand for Shell’s products; (c) currency fluctuations; (d) drilling and production results; (e) reserves estimates; (f) loss of market share and industry competition; (g) environmental and physical risks, including climate change; (h) risks associated with the identification of suitable potential acquisition properties and targets, and successful negotiation and completion of such transactions; (i) the risk of doing business in developing countries and countries subject to international sanctions; (j) legislative, judicial, fiscal and regulatory developments including tariffs and regulatory measures addressing climate change; (k) economic and financial market conditions in various countries and regions; (l) political risks, including the risks of expropriation and renegotiation of the terms of contracts with governmental entities, delays or advancements in the approval of projects and delays in the reimbursement for shared costs; (m) risks associated with the impact of pandemics, regional conflicts, such as the Russia-Ukraine war and the conflict in the Middle East, and a significant cyber security, data privacy or IT incident; (n) the pace of the energy transition; and (o) changes in trading conditions. No assurance is provided that future dividend payments will match or exceed previous dividend payments. All forward-looking statements contained in this content are expressly qualified in their entirety by the cautionary statements contained or referred to in this section. Readers should not place undue reliance on forward-looking statements. Additional risk factors that may affect future results are contained in Shell plc’s Form 20-F for the year ended December 31, 2025 (available at www.shell.com/investors/news-and-filings/sec-filings.html and www.sec.gov). These risk factors also expressly qualify all forward-looking statements contained in this content and should be considered by the reader. Each forward-looking statement speaks only as of the date of the publication mentioned in this website. Neither Shell plc nor any of its subsidiaries undertake any obligation to publicly update or revise any forward-looking statement as a result of new information, future events or other information. In light of these risks, results could differ materially from those stated, implied or inferred from the forward-looking statements contained in this content.
Shell’s net carbon intensity and net-zero emissions target
In this content we may refer to Shell’s “net carbon intensity” (NCI), which includes Shell’s carbon emissions from the production of our energy products, our suppliers’ carbon emissions in supplying energy for that production and our customers’ carbon emissions associated with their use of the energy products we sell. Shell’s NCI also includes the emissions associated with the production and use of energy products produced by others which Shell purchases for resale. Shell only controls its own emissions. The use of the terms Shell’s “net carbon intensity” or NCI is for convenience only and not intended to suggest these emissions are those of Shell plc or its subsidiaries.
Shell’s operating plan and outlook are forecasted for a three-year period and ten-year period, respectively, and are updated every year. They reflect the current economic environment and what we can reasonably expect to see over the next three and ten years. Accordingly, the outlook reflects our combined Scope 1 and 2 target, NCI target and our oil products ambition over the next ten years. However, Shell’s operating plan and outlook cannot reflect our 2050 net-zero emissions target, as this target is outside our planning period. Such future operating plans and outlooks could include changes to our portfolio, efficiency improvements and the use of carbon capture and storage and carbon credits. In the future, as society moves towards net-zero emissions, we expect Shell’s operating plans and outlooks to reflect this movement. However, if society is not net zero in 2050, as of today, there would be significant risk that Shell may not meet this target.
The information provided above regarding Shell’s NCI and net zero emissions target are not intended, nor should they be construed as introducing, suggesting or making any claim, target or representation thereof other than what is included in the content.
Forward-Looking non-GAAP measures
This content may contain certain forward-looking non-GAAP measures such as free cash flow and underlying operating expenses. We are unable to provide a reconciliation of these forward-looking non-GAAP measures to the most comparable GAAP financial measures because certain information needed to reconcile those non-GAAP measures to the most comparable GAAP financial measures is dependent on future events some of which are outside the control of Shell, such as oil and gas prices, interest rates and exchange rates. Moreover, estimating such GAAP measures with the required precision necessary to provide a meaningful reconciliation is extremely difficult and could not be accomplished without unreasonable effort. Non-GAAP measures in respect of future periods which cannot be reconciled to the most comparable GAAP financial measure are calculated in a manner which is consistent with the accounting policies applied in Shell plc’s consolidated financial statements. These forward-looking non-GAAP measures are provided to assist readers in understanding management’s use and expectations of such measures and may not be appropriate for other purposes.
The contents of websites referred to in this content do not form part of this content.
We may have used certain terms, such as resources, in this content that the United States Securities and Exchange Commission (SEC) strictly prohibits us from including in our filings with the SEC. Investors are urged to consider closely the disclosure in our Form 20-F, File No 1-32575, available on the SEC website www.sec.gov.