Faster refuelling for new generations of aircraft
Since the 1930s, when commercial aviation first started to see rapid growth, new generations of aircraft with the capacity to carry more passengers and cargo further have regularly come into service. With these new airliners, the demands on the infrastructure needed to service and support airlines and airports grew too.
The challenge for ground operations was to deliver greater volumes of fuel to these larger aircraft and to fill them as fast and as safely as possible to minimise turnaround times.
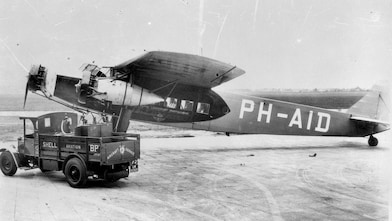
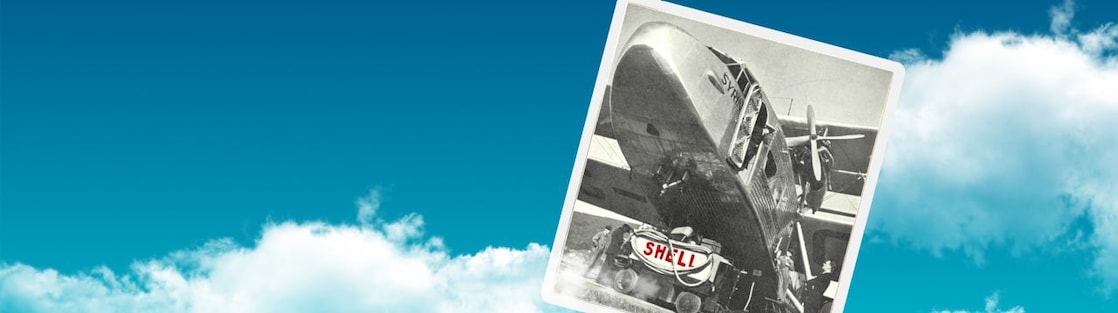
A major part of the answer lay in the development and deployment of larger refuelling trucks. In 1934, Shell Aviation introduced a new fuel tanker with the latest filters, water detection equipment and sophisticated meters, which would become the industry standard until after the Second World War. Safety features on the new truck included anti-static devices to reduce the risk of fire.
The lorry had a double rear-axle drive, and when fully loaded, was capable of operating in mud or sand without using track chains. It had a fuel tank capacity of 700 gallons and could fuel aircraft at a speed of up to 70 gallons per minute through four delivery hoses.
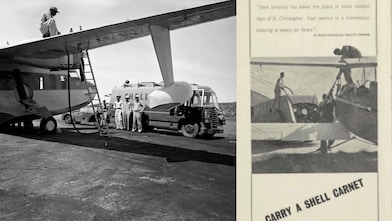
With aircraft size and range again growing swiftly in the late 1940s, the need to speed up refuelling further became apparent. Shell Aviation worked closely with vehicle manufacturers, such as S.A.I. Viberti-Turin of Italy and in 1949, introduced two new trucks, the Derby and the Devon, to provide faster refuelling. The Derby, with its single compartment tank of 2,500 gallons capacity, was the larger of the new arrivals. Its two pumps could supply a maximum delivery speed of 400 gallons a minute, making it ideal for refuelling the new generation of aircraft, like Boeing’s four-engine Stratocruiser.
Faster refuelling speeds introduced another challenge; the need for filters capable of dealing with the far higher liquid throughput, while continuing to remove solid particle contaminants, which could damage the aircraft’s engines and cause accidents. This tough challenge was solved by Shell with the TB Microfilter, fitted on both new models.
The year 1970 bought perhaps the biggest challenge for ground operations yet, how to efficiently refuel Boeing’s new 747 Jumbo Jet, with a massive fuel tank capacity of 42,000 gallons.
Although Shell had led the development and roll out of hydrant systems, many airports still relied on refuelling by truck. In the late 1960s, the company had anticipated the challenges that the 747 would bring and began to prepare for its arrival. Working with the UK’s well-established refuelling truck manufacturer John Thompson Brothers, it developed a larger transporter for use at airports without hydrant systems. The result was the London, launched in 1968. The rigid fueller and trailer combination had a capacity of 16,000 gallons and a maximum refuelling rate of 850 gallons per minute through two hoses. This meant it was more than capable of meeting the requirements of the new Jumbo Jet, helping to ensure airlines and their passengers continued to take-off on time, despite the massive increase in fuel load required.
Sources:
Shell Aviation News, 1949, p. 2, 58, 85, 166 and 250.
R. van Egmond and A. Westra, Shell and aviation. The story of more than a century of collaboration. Shell International B.V., 2019, p. 74-75.
Shell Aviation News, 1968, p. 188-189.
R. van Egmond and A. Westra, Shell and aviation. The story of more than a century of collaboration. Shell International B.V., 2019, p. 77.
Shell Aviation News, 1954, p. 31.
Shell Aviation News, 1956, p. 174-177.
Shell Aviation News, 1957, p. 300.
Shell historical archives.
Disclaimer
Disclaimer
Cautionary Note
The companies in which Shell plc directly and indirectly owns investments are separate legal entities. In this content “Shell”, “Shell Group” and “Group” are sometimes used for convenience to reference Shell plc and its subsidiaries in general. Likewise, the words “we”, “us” and “our” are also used to refer to Shell plc and its subsidiaries in general or to those who work for them. These terms are also used where no useful purpose is served by identifying the particular entity or entities. ‘‘Subsidiaries’’, “Shell subsidiaries” and “Shell companies” as used in this content refer to entities over which Shell plc either directly or indirectly has control. The terms “joint venture”, “joint operations”, “joint arrangements”, and “associates” may also be used to refer to a commercial arrangement in which Shell has a direct or indirect ownership interest with one or more parties. The term “Shell interest” is used for convenience to indicate the direct and/or indirect ownership interest held by Shell in an entity or unincorporated joint arrangement, after exclusion of all third-party interest.
Forward-Looking statements
This content contains forward-looking statements (within the meaning of the U.S. Private Securities Litigation Reform Act of 1995) concerning the financial condition, results of operations and businesses of Shell. All statements other than statements of historical fact are, or may be deemed to be, forward-looking statements. Forward-looking statements are statements of future expectations that are based on management’s current expectations and assumptions, including (without limitation) those concerning Shell’s strategy and operating plans, macroeconomic conditions, future energy demand, supply and product mix, commodity prices, demand for Shell’s products, production results and reserve estimates, development, execution and management of projects, energy transition and climate change, management of safety and environmental risks, costs, cash capital expenditures, technology advancements, legislative, judicial, fiscal and regulatory developments, regional conflicts and trading conditions, and involve known and unknown risks and uncertainties that could cause actual results, performance or events to differ materially from those expressed or implied in these statements. Forward-looking statements include, among other things, statements concerning the potential exposure of Shell to market risks and statements expressing management’s expectations, beliefs, estimates, forecasts, projections and assumptions. These forward-looking statements are identified by their use of terms and phrases such as “aim”; “ambition”; ‘‘anticipate’’; “aspire”, “aspiration”, ‘‘believe’’; “commit”; “commitment”; ‘‘could’’; “desire”; ‘‘estimate’’; ‘‘expect’’; ‘‘goals’’; ‘‘intend’’; ‘‘may’’; “milestones”; ‘‘objectives’’; ‘‘outlook’’; ‘‘plan’’; ‘‘probably’’; ‘‘project’’; ‘‘risks’’; “schedule”; ‘‘seek’’; ‘‘should’’; ‘‘target’’; “vision”; ‘‘will’’; “would” and similar terms and phrases. There are a number of factors that could affect the future operations of Shell and could cause those results to differ materially from those expressed in the forward-looking statements included in this content, including (without limitation): (a) price fluctuations in crude oil and natural gas; (b) changes in demand for Shell’s products; (c) currency fluctuations; (d) drilling and production results; (e) reserves estimates; (f) loss of market share and industry competition; (g) environmental and physical risks, including climate change; (h) risks associated with the identification of suitable potential acquisition properties and targets, and successful negotiation and completion of such transactions; (i) the risk of doing business in developing countries and countries subject to international sanctions; (j) legislative, judicial, fiscal and regulatory developments including tariffs and regulatory measures addressing climate change; (k) economic and financial market conditions in various countries and regions; (l) political risks, including the risks of expropriation and renegotiation of the terms of contracts with governmental entities, delays or advancements in the approval of projects and delays in the reimbursement for shared costs; (m) risks associated with the impact of pandemics, regional conflicts, such as the Russia-Ukraine war and the conflict in the Middle East, and a significant cyber security, data privacy or IT incident; (n) the pace of the energy transition; and (o) changes in trading conditions. No assurance is provided that future dividend payments will match or exceed previous dividend payments. All forward-looking statements contained in this content are expressly qualified in their entirety by the cautionary statements contained or referred to in this section. Readers should not place undue reliance on forward-looking statements. Additional risk factors that may affect future results are contained in Shell plc’s Form 20-F for the year ended December 31, 2025 (available at www.shell.com/investors/news-and-filings/sec-filings.html and www.sec.gov). These risk factors also expressly qualify all forward-looking statements contained in this content and should be considered by the reader. Each forward-looking statement speaks only as of the date of the publication mentioned in this website. Neither Shell plc nor any of its subsidiaries undertake any obligation to publicly update or revise any forward-looking statement as a result of new information, future events or other information. In light of these risks, results could differ materially from those stated, implied or inferred from the forward-looking statements contained in this content.
Shell’s net carbon intensity and net-zero emissions target
In this content we may refer to Shell’s “net carbon intensity” (NCI), which includes Shell’s carbon emissions from the production of our energy products, our suppliers’ carbon emissions in supplying energy for that production and our customers’ carbon emissions associated with their use of the energy products we sell. Shell’s NCI also includes the emissions associated with the production and use of energy products produced by others which Shell purchases for resale. Shell only controls its own emissions. The use of the terms Shell’s “net carbon intensity” or NCI is for convenience only and not intended to suggest these emissions are those of Shell plc or its subsidiaries.
Shell’s operating plan and outlook are forecasted for a three-year period and ten-year period, respectively, and are updated every year. They reflect the current economic environment and what we can reasonably expect to see over the next three and ten years. Accordingly, the outlook reflects our combined Scope 1 and 2 target, NCI target and our oil products ambition over the next ten years. However, Shell’s operating plan and outlook cannot reflect our 2050 net-zero emissions target, as this target is outside our planning period. Such future operating plans and outlooks could include changes to our portfolio, efficiency improvements and the use of carbon capture and storage and carbon credits. In the future, as society moves towards net-zero emissions, we expect Shell’s operating plans and outlooks to reflect this movement. However, if society is not net zero in 2050, as of today, there would be significant risk that Shell may not meet this target.
The information provided above regarding Shell’s NCI and net zero emissions target are not intended, nor should they be construed as introducing, suggesting or making any claim, target or representation thereof other than what is included in the content.
Forward-Looking non-GAAP measures
This content may contain certain forward-looking non-GAAP measures such as free cash flow and underlying operating expenses. We are unable to provide a reconciliation of these forward-looking non-GAAP measures to the most comparable GAAP financial measures because certain information needed to reconcile those non-GAAP measures to the most comparable GAAP financial measures is dependent on future events some of which are outside the control of Shell, such as oil and gas prices, interest rates and exchange rates. Moreover, estimating such GAAP measures with the required precision necessary to provide a meaningful reconciliation is extremely difficult and could not be accomplished without unreasonable effort. Non-GAAP measures in respect of future periods which cannot be reconciled to the most comparable GAAP financial measure are calculated in a manner which is consistent with the accounting policies applied in Shell plc’s consolidated financial statements. These forward-looking non-GAAP measures are provided to assist readers in understanding management’s use and expectations of such measures and may not be appropriate for other purposes.
The contents of websites referred to in this content do not form part of this content.
We may have used certain terms, such as resources, in this content that the United States Securities and Exchange Commission (SEC) strictly prohibits us from including in our filings with the SEC. Investors are urged to consider closely the disclosure in our Form 20-F, File No 1-32575, available on the SEC website www.sec.gov.