Flying around the world
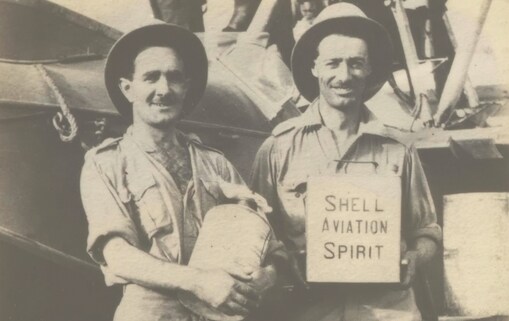
Following the rapid advance of aircraft technology during the First World War, aviators continued to push the boundaries of aircraft performance and endurance throughout the 1920s. By 1924, there were no fewer than six teams competing for the recognition of being the first to complete a round the world trip by air.
On 24 March 1924, a three-man British team was the first to set off on the attempt, led by Squadron Leader Archibald Stuart-MacLaren accompanied by flying officer William Noble Plenderleith and flight engineer Sergeant W H Andrews.
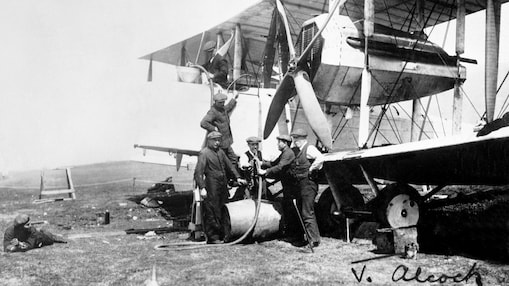
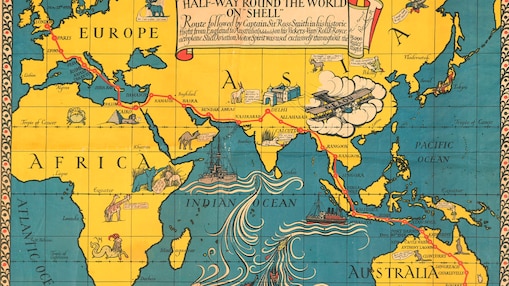
They took off on board their Vickers Vulture amphibious biplane with its single Napier Lion engine and wooden hull from the south coast of England. The flight was supported by Shell Aviation. The company was in the process of rolling out a global refuelling network and so was well placed to provide fuel and oil at each stop on the planned 23,000-mile journey.
The first stages of the trip were afflicted by bad weather and technical problems. By the time the team had reached India their aircraft had needed two replacement engines. But worse was to come, for the airframe was destroyed on take-off at Akyab Island in Burma.
In an act of great charity and collaboration, characteristic of many early aviators, who appreciated the dangers their fellow pioneers faced, the competing US team arranged for the delivery of a replacement aircraft from Tokyo to Akyab, enabling Stuart-MacLaren and his team to continue with their record-breaking attempt. They reached Hong Kong on 30 June, but disaster struck when on 4 August, heavy fog at Commander Islands in the Bering Sea off the coast of eastern Russia forced a sea landing that badly damaged the second Vulture.
The three intrepid aviators were rescued after beaching the aircraft and later learnt that their American rivals had become the first to achieve the feat of circumnavigating the world by air, landing in Seattle on the US west coast on 28 September 1924.
Despite the challenges they faced Stuart-MacLaren and his team had carried on until it was impossible for them to go further, learning a vast amount about the challenges of long distance flight in the process. The hardships they faced would be almost impossible for today’s air crews to imagine, but in typical understated fashion Stuart-Maclaren said of the attempt: “It was just a busman’s holiday, taken as one would take hold of a bicycle and go on an ordinary journey.”
Shell continued with its work to establish a global refuelling infrastructure throughout the 1920s and 1930s, helping to develop the safe, efficient refuelling network that provides the backbone of today’s global aviation industry.
Today round the world tickets are commonplace but the challenge has moved on to that of flying sustainably. In the same spirit of collaboration that drove the first aviator as they strove to fly further, higher and faster, Shell Aviation believes the whole aviation sector can come together, acting as pioneers together to accelerate progress towards net-zero emissions.
Sources:
Website BBC: ‘Attempted flight round the world 1924’, http://www.bbc.co.uk/ahistoryoftheworld/objects/CuOnyI1EQcW1s8sK6dg4Ag
Website New Forest Knowledge: ‘Around the World Flight Attempt in 1924’, https://nfknowledge.org/contributions/around-the-world-flight-attempt-in-1924/#map=10/-1.31/NaN/0/24:0:0.6|39:1:1|40:1:1
Shell Aviation News, 1939.
Shell historical archives.
More Stories
Disclaimer
Disclaimer
Cautionary Note
The companies in which Shell plc directly and indirectly owns investments are separate legal entities. In this content “Shell”, “Shell Group” and “Group” are sometimes used for convenience to reference Shell plc and its subsidiaries in general. Likewise, the words “we”, “us” and “our” are also used to refer to Shell plc and its subsidiaries in general or to those who work for them. These terms are also used where no useful purpose is served by identifying the particular entity or entities. ‘‘Subsidiaries’’, “Shell subsidiaries” and “Shell companies” as used in this content refer to entities over which Shell plc either directly or indirectly has control. The terms “joint venture”, “joint operations”, “joint arrangements”, and “associates” may also be used to refer to a commercial arrangement in which Shell has a direct or indirect ownership interest with one or more parties. The term “Shell interest” is used for convenience to indicate the direct and/or indirect ownership interest held by Shell in an entity or unincorporated joint arrangement, after exclusion of all third-party interest.
Forward-Looking statements
This content contains forward-looking statements (within the meaning of the U.S. Private Securities Litigation Reform Act of 1995) concerning the financial condition, results of operations and businesses of Shell. All statements other than statements of historical fact are, or may be deemed to be, forward-looking statements. Forward-looking statements are statements of future expectations that are based on management’s current expectations and assumptions, including (without limitation) those concerning Shell’s strategy and operating plans, macroeconomic conditions, future energy demand, supply and product mix, commodity prices, demand for Shell’s products, production results and reserve estimates, development, execution and management of projects, energy transition and climate change, management of safety and environmental risks, costs, cash capital expenditures, technology advancements, legislative, judicial, fiscal and regulatory developments, regional conflicts and trading conditions, and involve known and unknown risks and uncertainties that could cause actual results, performance or events to differ materially from those expressed or implied in these statements. Forward-looking statements include, among other things, statements concerning the potential exposure of Shell to market risks and statements expressing management’s expectations, beliefs, estimates, forecasts, projections and assumptions. These forward-looking statements are identified by their use of terms and phrases such as “aim”; “ambition”; ‘‘anticipate’’; “aspire”, “aspiration”, ‘‘believe’’; “commit”; “commitment”; ‘‘could’’; “desire”; ‘‘estimate’’; ‘‘expect’’; ‘‘goals’’; ‘‘intend’’; ‘‘may’’; “milestones”; ‘‘objectives’’; ‘‘outlook’’; ‘‘plan’’; ‘‘probably’’; ‘‘project’’; ‘‘risks’’; “schedule”; ‘‘seek’’; ‘‘should’’; ‘‘target’’; “vision”; ‘‘will’’; “would” and similar terms and phrases. There are a number of factors that could affect the future operations of Shell and could cause those results to differ materially from those expressed in the forward-looking statements included in this content, including (without limitation): (a) price fluctuations in crude oil and natural gas; (b) changes in demand for Shell’s products; (c) currency fluctuations; (d) drilling and production results; (e) reserves estimates; (f) loss of market share and industry competition; (g) environmental and physical risks, including climate change; (h) risks associated with the identification of suitable potential acquisition properties and targets, and successful negotiation and completion of such transactions; (i) the risk of doing business in developing countries and countries subject to international sanctions; (j) legislative, judicial, fiscal and regulatory developments including tariffs and regulatory measures addressing climate change; (k) economic and financial market conditions in various countries and regions; (l) political risks, including the risks of expropriation and renegotiation of the terms of contracts with governmental entities, delays or advancements in the approval of projects and delays in the reimbursement for shared costs; (m) risks associated with the impact of pandemics, regional conflicts, such as the Russia-Ukraine war and the conflict in the Middle East, and a significant cyber security, data privacy or IT incident; (n) the pace of the energy transition; and (o) changes in trading conditions. No assurance is provided that future dividend payments will match or exceed previous dividend payments. All forward-looking statements contained in this content are expressly qualified in their entirety by the cautionary statements contained or referred to in this section. Readers should not place undue reliance on forward-looking statements. Additional risk factors that may affect future results are contained in Shell plc’s Form 20-F for the year ended December 31, 2025 (available at www.shell.com/investors/news-and-filings/sec-filings.html and www.sec.gov). These risk factors also expressly qualify all forward-looking statements contained in this content and should be considered by the reader. Each forward-looking statement speaks only as of the date of this content. Neither Shell plc nor any of its subsidiaries undertake any obligation to publicly update or revise any forward-looking statement as a result of new information, future events or other information. In light of these risks, results could differ materially from those stated, implied or inferred from the forward-looking statements contained in this content.
Shell’s net carbon intensity and net-zero emissions target
In this content we may refer to Shell’s “net carbon intensity” (NCI), which includes Shell’s carbon emissions from the production of our energy products, our suppliers’ carbon emissions in supplying energy for that production and our customers’ carbon emissions associated with their use of the energy products we sell. Shell’s NCI also includes the emissions associated with the production and use of energy products produced by others which Shell purchases for resale. Shell only controls its own emissions. The use of the terms Shell’s “net carbon intensity” or NCI is for convenience only and not intended to suggest these emissions are those of Shell plc or its subsidiaries.
Shell’s operating plan and outlook are forecasted for a three-year period and ten-year period, respectively, and are updated every year. They reflect the current economic environment and what we can reasonably expect to see over the next three and ten years. Accordingly, the outlook reflects our combined Scope 1 and 2 target, NCI target and our oil products ambition over the next ten years. However, Shell’s operating plan and outlook cannot reflect our 2050 net-zero emissions target, as this target is outside our planning period. Such future operating plans and outlooks could include changes to our portfolio, efficiency improvements and the use of carbon capture and storage and carbon credits. In the future, as society moves towards net-zero emissions, we expect Shell’s operating plans and outlooks to reflect this movement. However, if society is not net zero in 2050, as of today, there would be significant risk that Shell may not meet this target.
The information provided above regarding Shell’s NCI and net zero emissions target are not intended, nor should they be construed as introducing, suggesting or making any claim, target or representation thereof other than what is included in the content.
Forward-Looking non-GAAP measures
This content may contain certain forward-looking non-GAAP measures such as free cash flow and underlying operating expenses. We are unable to provide a reconciliation of these forward-looking non-GAAP measures to the most comparable GAAP financial measures because certain information needed to reconcile those non-GAAP measures to the most comparable GAAP financial measures is dependent on future events some of which are outside the control of Shell, such as oil and gas prices, interest rates and exchange rates. Moreover, estimating such GAAP measures with the required precision necessary to provide a meaningful reconciliation is extremely difficult and could not be accomplished without unreasonable effort. Non-GAAP measures in respect of future periods which cannot be reconciled to the most comparable GAAP financial measure are calculated in a manner which is consistent with the accounting policies applied in Shell plc’s consolidated financial statements. These forward-looking non-GAAP measures are provided to assist readers in understanding management’s use and expectations of such measures and may not be appropriate for other purposes.
The contents of websites referred to in this content do not form part of this content.
We may have used certain terms, such as resources, in this content that the United States Securities and Exchange Commission (SEC) strictly prohibits us from including in our filings with the SEC. Investors are urged to consider closely the disclosure in our Form 20-F, File No 1-32575, available on the SEC website www.sec.gov.