Alcock and Brown conquer the Atlantic
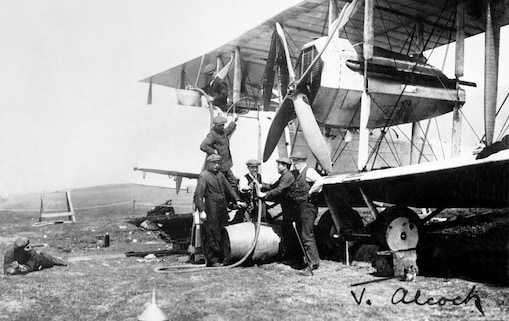
By 1919, with aircraft capable of flying further and staying airborne for longer, a new challenge loomed large in the sights of aviation’s pioneers – the first non-stop transatlantic crossing.
British aviators, John Alcock and Arthur Brown set off from Lester’s Field, St Johns on the tip of Newfoundland, at around 1.45pm on 15 June, determined to be the first to make the crossing. Their Vickers Vimy aircraft, a First World War bomber powered by two Rolls-Royce Eagle 360hp engines, had its bomb racks replaced with extra fuel tanks for the record-breaking attempt. They took to the air with 865 gallons of fuel, supplied by Shell, as part of its on-going support for the early pioneers of aviation, which has seen its fuel power a number of record breaking flights, including Louis Blériot’s first crossing of the English Channel, ten years earlier. Australian brothers Ross and Keith Smith would also complete the first flight to Australia in December of 1919, again aboard a Vickers Vimy, powered by Rolls-Royce engines and fuelled by Shell.
Alcock and Brown’s challenges started at take-off, with the overloaded aircraft having difficulty getting airborne from the rough field and barely missing the treetops as it struggled to get aloft. The aircraft’s wind-driven electrical generator failed just four hours into the attempt, depriving the crew of radio contact, intercom and heating. During the flight, bad weather made navigation and control of the Vimy extremely hazardous, with thick fog preventing navigator, Brown, from using his sextant to navigate.
However, as dawn broke the west of Ireland came into sight and the pair made landfall in County Galway at 8.40am. The aircraft went nose-over on landing because what was apparently a green field turned out to be a bog, but neither airman was hurt. As the headline on 16 June in The New York Times proclaimed: “Alcock and Brown fly across Atlantic: make 1,890 miles in 16 hours, 12 minutes; sometimes upside down in dense, icy fog.” This first transatlantic flight made instant heroes of the pair, and they received an award from the London Daily Mail of £10,000 for the feat and both were knighted a few days later by King George V.
Shell’s support for aviation’s pioneers continued and in 1976, just 57 years later, it worked closely with Rolls-Royce to supply fuel and lubricants for the first flight of Concorde from London to Bahrain. In the same year, the supersonic airliner went into service flying passengers across the Atlantic in just three and half hours.1
Sources:
1 https://www.britannica.com/technology/Concorde
Website Aviation History: Airmen – Alcock and Brown, http://www.aviation-history.com/airmen/alcock.htm
Website Waymarking: First non-stop transatlantic flight - Clifden, Ireland: http://www.waymarking.com/waymarks/WM77T3_First_non_stop_transatlantic_flight_Clifden_Ireland_EU
Website University of Cambridge: ‘The first non-stop transatlantic air crossing - 100 years on’, https://www.cam.ac.uk/Transatlantic100
R. van Egmond and A. Westra, Shell and aviation. The story of more than a century of collaboration. Shell International B.V., 2019, p. 42-43, 80-81
Shell historical archives.
Our Stories
More Stories
Disclaimer
Disclaimer
Cautionary Note
The companies in which Shell plc directly and indirectly owns investments are separate legal entities. In this content “Shell”, “Shell Group” and “Group” are sometimes used for convenience to reference Shell plc and its subsidiaries in general. Likewise, the words “we”, “us” and “our” are also used to refer to Shell plc and its subsidiaries in general or to those who work for them. These terms are also used where no useful purpose is served by identifying the particular entity or entities. ‘‘Subsidiaries’’, “Shell subsidiaries” and “Shell companies” as used in this content refer to entities over which Shell plc either directly or indirectly has control. The terms “joint venture”, “joint operations”, “joint arrangements”, and “associates” may also be used to refer to a commercial arrangement in which Shell has a direct or indirect ownership interest with one or more parties. The term “Shell interest” is used for convenience to indicate the direct and/or indirect ownership interest held by Shell in an entity or unincorporated joint arrangement, after exclusion of all third-party interest.
Forward-Looking statements
This content contains forward-looking statements (within the meaning of the U.S. Private Securities Litigation Reform Act of 1995) concerning the financial condition, results of operations and businesses of Shell. All statements other than statements of historical fact are, or may be deemed to be, forward-looking statements. Forward-looking statements are statements of future expectations that are based on management’s current expectations and assumptions, including (without limitation) those concerning Shell’s strategy and operating plans, macroeconomic conditions, future energy demand, supply and product mix, commodity prices, demand for Shell’s products, production results and reserve estimates, development, execution and management of projects, energy transition and climate change, management of safety and environmental risks, costs, cash capital expenditures, technology advancements, legislative, judicial, fiscal and regulatory developments, regional conflicts and trading conditions, and involve known and unknown risks and uncertainties that could cause actual results, performance or events to differ materially from those expressed or implied in these statements. Forward-looking statements include, among other things, statements concerning the potential exposure of Shell to market risks and statements expressing management’s expectations, beliefs, estimates, forecasts, projections and assumptions. These forward-looking statements are identified by their use of terms and phrases such as “aim”; “ambition”; ‘‘anticipate’’; “aspire”, “aspiration”, ‘‘believe’’; “commit”; “commitment”; ‘‘could’’; “desire”; ‘‘estimate’’; ‘‘expect’’; ‘‘goals’’; ‘‘intend’’; ‘‘may’’; “milestones”; ‘‘objectives’’; ‘‘outlook’’; ‘‘plan’’; ‘‘probably’’; ‘‘project’’; ‘‘risks’’; “schedule”; ‘‘seek’’; ‘‘should’’; ‘‘target’’; “vision”; ‘‘will’’; “would” and similar terms and phrases. There are a number of factors that could affect the future operations of Shell and could cause those results to differ materially from those expressed in the forward-looking statements included in this content, including (without limitation): (a) price fluctuations in crude oil and natural gas; (b) changes in demand for Shell’s products; (c) currency fluctuations; (d) drilling and production results; (e) reserves estimates; (f) loss of market share and industry competition; (g) environmental and physical risks, including climate change; (h) risks associated with the identification of suitable potential acquisition properties and targets, and successful negotiation and completion of such transactions; (i) the risk of doing business in developing countries and countries subject to international sanctions; (j) legislative, judicial, fiscal and regulatory developments including tariffs and regulatory measures addressing climate change; (k) economic and financial market conditions in various countries and regions; (l) political risks, including the risks of expropriation and renegotiation of the terms of contracts with governmental entities, delays or advancements in the approval of projects and delays in the reimbursement for shared costs; (m) risks associated with the impact of pandemics, regional conflicts, such as the Russia-Ukraine war and the conflict in the Middle East, and a significant cyber security, data privacy or IT incident; (n) the pace of the energy transition; and (o) changes in trading conditions. No assurance is provided that future dividend payments will match or exceed previous dividend payments. All forward-looking statements contained in this content are expressly qualified in their entirety by the cautionary statements contained or referred to in this section. Readers should not place undue reliance on forward-looking statements. Additional risk factors that may affect future results are contained in Shell plc’s Form 20-F for the year ended December 31, 2025 (available at www.shell.com/investors/news-and-filings/sec-filings.html and www.sec.gov). These risk factors also expressly qualify all forward-looking statements contained in this content and should be considered by the reader. Each forward-looking statement speaks only as of the date of the publication mentioned in this website. Neither Shell plc nor any of its subsidiaries undertake any obligation to publicly update or revise any forward-looking statement as a result of new information, future events or other information. In light of these risks, results could differ materially from those stated, implied or inferred from the forward-looking statements contained in this content.
Shell’s net carbon intensity and net-zero emissions target
In this content we may refer to Shell’s “net carbon intensity” (NCI), which includes Shell’s carbon emissions from the production of our energy products, our suppliers’ carbon emissions in supplying energy for that production and our customers’ carbon emissions associated with their use of the energy products we sell. Shell’s NCI also includes the emissions associated with the production and use of energy products produced by others which Shell purchases for resale. Shell only controls its own emissions. The use of the terms Shell’s “net carbon intensity” or NCI is for convenience only and not intended to suggest these emissions are those of Shell plc or its subsidiaries.
Shell’s operating plan and outlook are forecasted for a three-year period and ten-year period, respectively, and are updated every year. They reflect the current economic environment and what we can reasonably expect to see over the next three and ten years. Accordingly, the outlook reflects our combined Scope 1 and 2 target, NCI target and our oil products ambition over the next ten years. However, Shell’s operating plan and outlook cannot reflect our 2050 net-zero emissions target, as this target is outside our planning period. Such future operating plans and outlooks could include changes to our portfolio, efficiency improvements and the use of carbon capture and storage and carbon credits. In the future, as society moves towards net-zero emissions, we expect Shell’s operating plans and outlooks to reflect this movement. However, if society is not net zero in 2050, as of today, there would be significant risk that Shell may not meet this target.
The information provided above regarding Shell’s NCI and net zero emissions target are not intended, nor should they be construed as introducing, suggesting or making any claim, target or representation thereof other than what is included in the content.
Forward-Looking non-GAAP measures
This content may contain certain forward-looking non-GAAP measures such as free cash flow and underlying operating expenses. We are unable to provide a reconciliation of these forward-looking non-GAAP measures to the most comparable GAAP financial measures because certain information needed to reconcile those non-GAAP measures to the most comparable GAAP financial measures is dependent on future events some of which are outside the control of Shell, such as oil and gas prices, interest rates and exchange rates. Moreover, estimating such GAAP measures with the required precision necessary to provide a meaningful reconciliation is extremely difficult and could not be accomplished without unreasonable effort. Non-GAAP measures in respect of future periods which cannot be reconciled to the most comparable GAAP financial measure are calculated in a manner which is consistent with the accounting policies applied in Shell plc’s consolidated financial statements. These forward-looking non-GAAP measures are provided to assist readers in understanding management’s use and expectations of such measures and may not be appropriate for other purposes.
The contents of websites referred to in this content do not form part of this content.
We may have used certain terms, such as resources, in this content that the United States Securities and Exchange Commission (SEC) strictly prohibits us from including in our filings with the SEC. Investors are urged to consider closely the disclosure in our Form 20-F, File No 1-32575, available on the SEC website www.sec.gov.